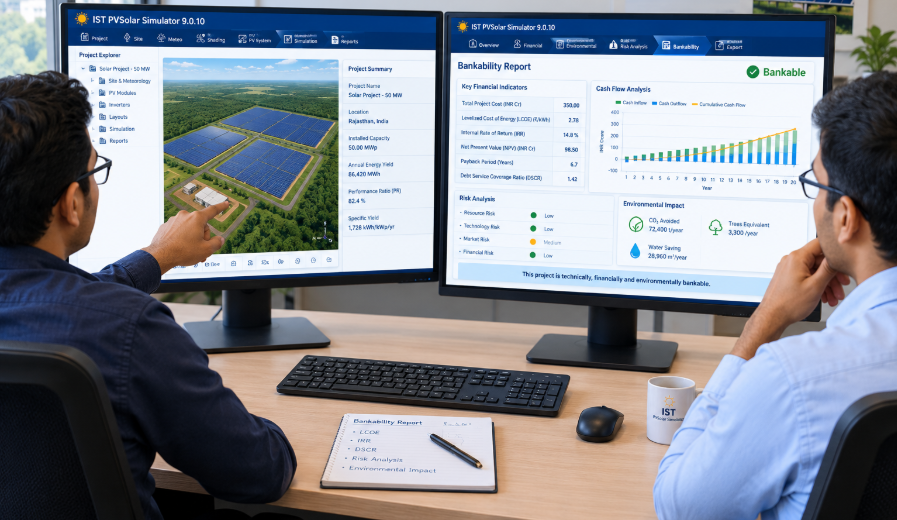
From Simulation to Signature: The Bankability Report in IST PVSolar Simulator 9.0.10
A yield simulation tells an investor what a solar plant should produce. A bankability report tells a lender whether they should actually write the check. Those are different documents with different audiences, different structure, and — critically — different standards of proof. IST PVSolar Simulator 9.0.10 generates both from the same project, and the bankability report it produces is a genuine 12-section technical and financial due-diligence document, not a rebadged summary of the simulation tab.
That's exactly what the Bankability Assessment Report feature in IST PVSolar Simulator is built to produce. It turns the plant you've already designed and simulated into a due-diligence-ready document, in the same structural language that project-finance lenders and IEs expect.
It opens like a real due-diligence deliverable structured like one
The report starts with a cover page carrying a confidentiality classification ("Strictly Confidential — For Addressee Only"), project name, software version, date of issue, preparer and preparer credentials, the addressee ("Prepared For"), and a revision status field. It also carries an explicit, hard-to-miss disclaimer: the document is flagged as developer-prepared, pending independent engineer certification, and states plainly that it should not be relied upon by a lender or investor for a financing decision until that independent review is complete. That's an honest and important distinction — this tool produces the analytical backbone a certifying engineer would review and sign off on, not a substitute for that certification.
The twelve sections, and what each one actually assesses
- Executive Summary — opens with three headline verdicts side by side: Technology Bankability, Developer & EPC Bankability, and Project-Level Bankability, each with its own pass/marginal/fail-style status card, before the narrative detail begins.
- Project Overview — the site, system configuration, and design basis in one place.
- Technology Bankability Assessment — this is where component-level scrutiny happens. PV modules are checked against a BNEF Tier 1 status field, years in production, cumulative shipments, quality certifications, and warranty terms and warranty creditworthiness. A technical specification table then compares the selected module's actual cell technology, STC power, efficiency, and temperature coefficient against stated industry benchmark ranges (e.g., ">20% efficiency", "<-0.35%/°C") — so a reviewer can see at a glance whether the chosen hardware sits inside or outside typical bankable ranges, not just what its numbers are.
- Developer & EPC Bankability Assessment — an EPC contract-terms review table (each provision given a status flag and a specific recommendation) plus a dedicated O&M contractor assessment, each rendered as a risk-labeled row rather than free text.
- Project-Level Bankability Assessment — this is where the numbers from the Economic Evaluation bankability: DSCR (minimum and average, tested over the loan tenure), LLCR (Loan Life Coverage Ratio), PLCR (Project Life Coverage Ratio), Equity IRR, Equity NPV, Equity Payback, and a composite Financial Risk Score (0–100, rating-agency style — Investment Grade / Sub-Investment Grade / Speculative) that combines Project IRR, Equity IRR, DSCR, LLCR, PLCR, and CAPEX/Wp against a country/region-specific bankability band, with a hard override: a negative NPV or a coverage ratio below 1.0x floors the score at Speculative regardless of what the average would otherwise say.
- Economic & Financial Evaluation — the full LCOE, NPV, IRR, payback, and revenue projection detail, all computed on the P90 (90% exceedance) energy basis — the conservative figure lenders actually underwrite against, not the P50 median a developer might prefer to show.
- Legal, Contractual & Conditions Precedent — the financing-agreement checklist layer: land title/lease status, PPA terms, permits, interconnection agreements — the conditions precedent a lender's counsel will actually check off before disbursement.
- Insurance, Country & Currency Risk — coverage adequacy and macro risk factors relevant to the specific jurisdiction.
- Environmental & Social Action Plan (ESAP) — the E&S compliance section increasingly required by DFI and green-bond-linked financing.
- Fiscal & Stress Testing — two distinct pieces here. First, a tax/depreciation/fiscal-incentive position table (depreciation method, tax holiday status, import duty/GST treatment) with an explicit warning that these vary materially by jurisdiction and directly affect the after-tax IRR — a caution against over-relying on the base-case Section 6 numbers without confirming local tax treatment. Second, a deterministic stress-scenario table: each scenario recomputes the minimum DSCR under a stressed assumption (holding the debt-service cash flow constant, reverse-engineered from the reported Average DSCR), with an honest footnote that this is an indicative approximation and a full cash-flow re-run is recommended for precise IRR sensitivity — the report doesn't overstate the precision of a quick stress table.
- Conclusions & Recommendations — the synthesized verdict and the specific action items behind it.
- Report Basis, Reliance & Documents Reviewed — the methodology and evidentiary trail: what inputs the assessment relied on, so a reviewer can trace every number back to its source.
Built on the same bankability engine that powers the in-app risk score
Why the structure matters more than the polish
A lender's technical advisor reading a bankability report isn't looking for a nicely formatted PDF — they're looking for exactly the kind of traceable, benchmark-referenced, appropriately-caveated structure this report follows: component specs checked against stated industry ranges rather than asserted as automatically fine, coverage ratios computed on the conservative P90 basis rather than an optimistic P50, stress scenarios labeled as approximations rather than dressed up as precise, and a clear, unambiguous statement that the document is a developer-prepared analytical basis awaiting independent certification — not a finished bankability opinion in itself. That's the difference between a report that helps a deal move forward and one that gets bounced back with questions.